If you are trying to learn how to overcome limiting beliefs about money, you may already recognize thoughts such as “I will always struggle,” “I am terrible with money,” or “financial security is for other people.” These beliefs can feel like facts because they have been repeated for years, but a belief is not automatically an accurate prediction of your future. The goal is not forced positivity; it is learning to question old conclusions and connect healthier thinking with practical financial behavior.
Money beliefs can develop through many influences. A review of financial-socialization research describes parental modeling, parent-child money discussions, and firsthand financial experiences as important pathways through which financial attitudes, knowledge, behaviors, and later financial well-being may develop.
The Consumer Financial Protection Bureau also describes financial habits and norms as involving values, attitudes, emotions, social expectations, routines, and contextual cues that can guide everyday financial decisions. These influences matter, but they do not mean your childhood, past mistakes, or present circumstances permanently determine what you can learn next.
A healthier money mindset is most useful when it helps you face reality more effectively. It should make planning, learning, saving, evaluating options, setting boundaries, and recovering from mistakes easier—not encourage you to believe that positive thoughts alone control financial outcomes.
Limiting beliefs about money → common money beliefs and how they influence financial habits
How to overcome limiting beliefs about money without forced positivity
Changing a money belief starts with understanding that financial outcomes and financial mindset are related but not identical. Your behavior matters, yet income, debt, employment, health, housing costs, family responsibilities, opportunity, economic conditions, and unexpected events also affect your finances.
The CFPB defines financial well-being in terms of security and freedom of choice. It includes having control over everyday finances, being able to absorb a financial shock, being on track toward financial goals, and having enough freedom to make meaningful choices.
That is a useful direction for money-mindset work. Instead of asking whether you can convince yourself that you are already wealthy, ask whether your beliefs help you move toward greater clarity, capability, security, and choice.
The following seven steps turn that idea into something practical.
1. Identify the Exact Belief Instead of Calling It a “Bad Mindset”
You cannot challenge a belief clearly until you know what it actually says. “I have a bad money mindset” is too broad. A specific thought such as “I can never keep money,” “I always mess up financially,” or “earning more will make people judge me” gives you something you can examine.
Pay attention to the sentences that appear during emotionally charged financial moments. You may notice them when checking an account balance, receiving a bill, considering an opportunity, making a purchase, discussing income, or comparing yourself with someone else.
Write the thought exactly as it appears.
For example:
Situation: I looked at my savings and felt behind.
Automatic belief: “I will never become financially secure.”
Emotion: Discouragement.
Usual reaction: Avoid looking at my finances again.
This exercise separates the thought from your identity. Instead of “This is who I am,” you begin with “This is a belief that appeared in this situation.”
That difference creates room for change.
2. Ask Where the Belief Came From—and Whether It Still Fits
Some money beliefs may reflect messages you absorbed from family, culture, relationships, past financial stress, or repeated experience. Perhaps you frequently heard “money does not grow on trees,” watched adults argue about finances, saw wealthy people described negatively, or experienced a period when money really was extremely scarce.
Understanding the origin can create context without turning the past into an excuse. Financial-socialization research supports the idea that parental modeling, explicit financial conversations, and experiential learning can influence later financial attitudes and behaviors.
Ask:
- When do I remember first thinking this way?
- Who or what reinforced this message?
- Was the belief useful or protective at one point?
- Is the same conclusion completely accurate in my life today?
- What has changed since I first learned it?
Suppose you grew up hearing, “Taking financial risks always ends badly.” That warning may have protected your family from genuine financial danger. As an adult, however, treating every career move, education expense, business idea, or investment decision as equally dangerous may prevent you from evaluating opportunities individually.
You do not have to reject everything you learned. You can keep the useful caution while changing the absolute rule.
Quick reflection
Complete these sentences:
I learned that money means __________.
That belief may have helped me by __________.
Today, the part that no longer serves me is __________.
3. Separate Facts From Predictions
Limiting beliefs often sound convincing because they begin with something true and then make a much larger prediction.
“I have debt” is a fact.
“I will always be in debt” is a prediction.
“I made an impulsive purchase” describes an event.
“I have no self-control with money” turns one pattern into an identity.
“My income is currently lower than I want” may be accurate.
“I can never increase my income” claims knowledge about the future.
When learning how to overcome limiting beliefs about money, this distinction can be one of the most powerful practical habits. You do not need to deny the difficult fact; you only need to stop adding conclusions that the evidence does not support.
Use this four-part structure:
FACT: What can I verify right now?
STORY: What am I adding to the fact?
BALANCED VIEW: What is a more complete interpretation?
ACTION: What can I influence next?
Example:
Fact: My emergency savings are only $300.
Story: I am hopeless at saving.
Balanced view: My savings are smaller than I want, but I already have evidence that I can keep some money aside.
Action: Decide on a realistic recurring savings amount.
The new perspective does not magically solve the financial problem. It makes a useful response more likely.
4. Create a Grounded Replacement Belief
People sometimes try to replace a negative money belief with the most positive statement possible. If you believe, “I will never have enough,” jumping immediately to “I have unlimited wealth” may create more resistance than confidence.
A bridge belief is often easier to use.
Try:
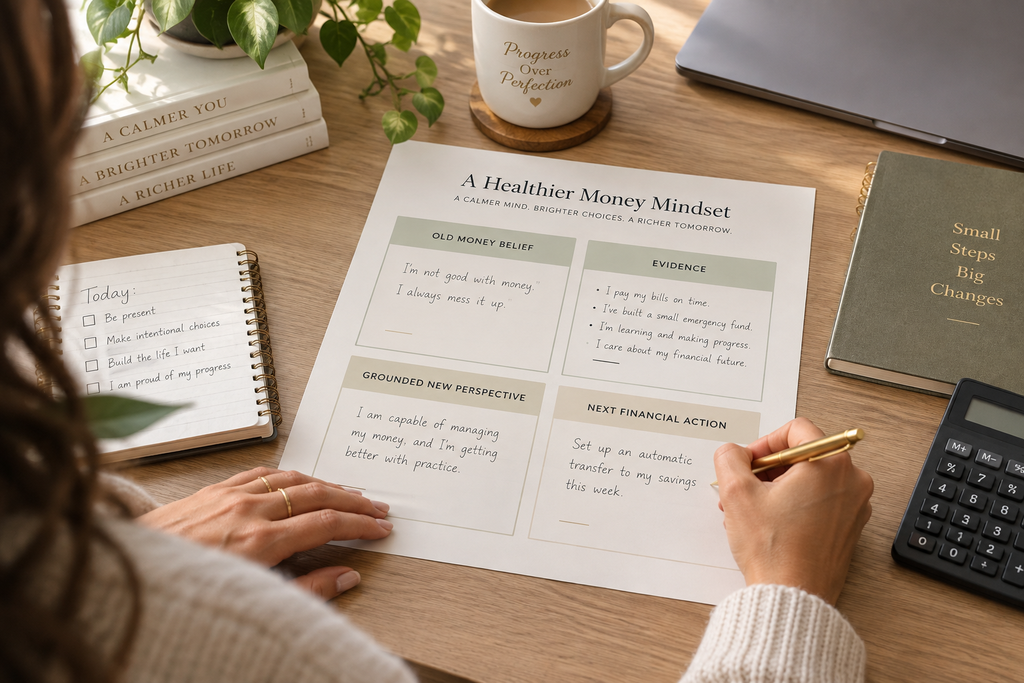
Old: “I am bad with money.”
Grounded: “I can improve specific financial skills.”
Old: “I can never save.”
Grounded: “I can practice keeping part of what I earn.”
Old: “I am too far behind.”
Grounded: “I can improve the next decision even if I cannot change the past.”
Old: “There are no opportunities for me.”
Grounded: “I can look for realistic opportunities and evaluate them carefully.”
Research on self-affirmation offers useful context. A 2025 meta-analysis summarized by the American Psychological Association reviewed 129 studies and found small positive effects across areas such as general well-being, self-perception, and reduced negative symptoms. These interventions typically involved reflecting on values, identity, and positive personal qualities rather than simply repeating desired material outcomes.
This makes grounded self-reflection a more responsible approach than treating an affirmation as a financial guarantee.
Where The Wealth Signal May Fit
Some readers prefer creating their own journal prompts, reflection exercises, affirmations, and mindset routines. Others like having a structured resource to keep the process organized.
That is where The Wealth Signal may have contextual relevance. The supplied official website could not be reliably fetched during research, so current product details such as creator information, format, modules, bonuses, price, guarantee terms, or claimed outcomes cannot be responsibly verified here.
For that reason, the product is best treated as optional mindset-oriented support rather than a substitute for financial planning, budgeting, saving, earning strategies, or qualified professional advice when needed.
If structured money-mindset guidance would help you stay focused, consider whether The Wealth Signal fits alongside the practical habits you are building.
5. Pair Every New Belief With One Financial Behavior
A new belief becomes much more meaningful when you can see it in your behavior.
Suppose your replacement belief is:
“I can become more intentional with money.”
What would intentional behavior look like today?
Maybe you review a recurring expense. Perhaps you wait 24 hours before a nonessential purchase. You could organize your bills, transfer money into savings, ask a financial question, or spend time developing a skill that supports future income.
Use this formula:
NEW BELIEF → BEHAVIOR → EVIDENCE
For example:
New belief: “I can become a consistent saver.”
Behavior: Transfer $20 after payday.
Evidence: “I kept part of what I earned this week.”
Another example:
New belief: “I can learn to make better financial decisions.”
Behavior: Research a financial term before acting.
Evidence: “I gathered information instead of deciding impulsively.”
The CFPB’s research on pathways to financial well-being found associations among financial skill, financial behavior, financial situation, and financial well-being. It also identified financial self-efficacy—confidence in one’s ability to achieve financial goals—as a factor associated with financial behavior.
This gives your mindset practice a grounded target. You are not trying only to feel confident; you are building evidence that supports greater confidence.
Money mindset exercises → practical exercises that connect money beliefs with everyday behavior
6. Change the Environment That Keeps Triggering the Old Pattern
Sometimes the problem is not a lack of positive thinking. Your environment may repeatedly make the old behavior easier.
If impulsive online shopping is a problem, saved payment information and promotional notifications reduce friction around buying. If saving is difficult, keeping every dollar in one easily spendable account may require you to make the same saving decision repeatedly.
The CFPB’s financial-education principles emphasize taking a person’s circumstances and environment into account and making good financial decisions easier to follow through on.
Practical environmental changes could include:
- automatically transferring an affordable amount to savings;
- disabling shopping notifications;
- removing saved card details from tempting sites;
- scheduling a weekly money review;
- setting bill reminders;
- keeping a written goal somewhere visible;
- creating a waiting period before nonessential purchases;
- blocking regular time for skill-building or income-related work.
The purpose is not to create a perfect environment. It is to reduce how often your better financial behavior depends entirely on willpower.
This is an important part of how to overcome limiting beliefs about money because repeated actions can begin creating a different story about what you are capable of.
If your old belief is “I never follow through,” a supportive system gives you more opportunities to demonstrate that you can.
7. Build a Record of Evidence for Your New Identity
Old beliefs are usually supported by a mental archive of every mistake you have made. You remember the overspending, missed opportunity, late payment, poor decision, or time you abandoned a savings plan.
You may pay much less attention to evidence of improvement.
Create a short “money evidence” record. Once a day or several times each week, note one behavior that supports the kind of financial identity you are trying to build.
Examples include:
- I opened a bill instead of avoiding it.
- I saved a small amount.
- I asked a useful question.
- I canceled something I no longer use.
- I resisted an emotional purchase.
- I applied for an opportunity.
- I learned one financial concept.
- I reviewed my goal.
- I admitted a mistake and corrected the next decision.
These actions may look small compared with a major financial goal, but they serve a different purpose. They show that your old identity statement is incomplete.
The CFPB highlights planning and goals, saving, bill payment, credit profile, and financial well-being among core financial capability outcomes. These are useful areas to track because they shift attention from vague feelings about money toward observable financial behavior.
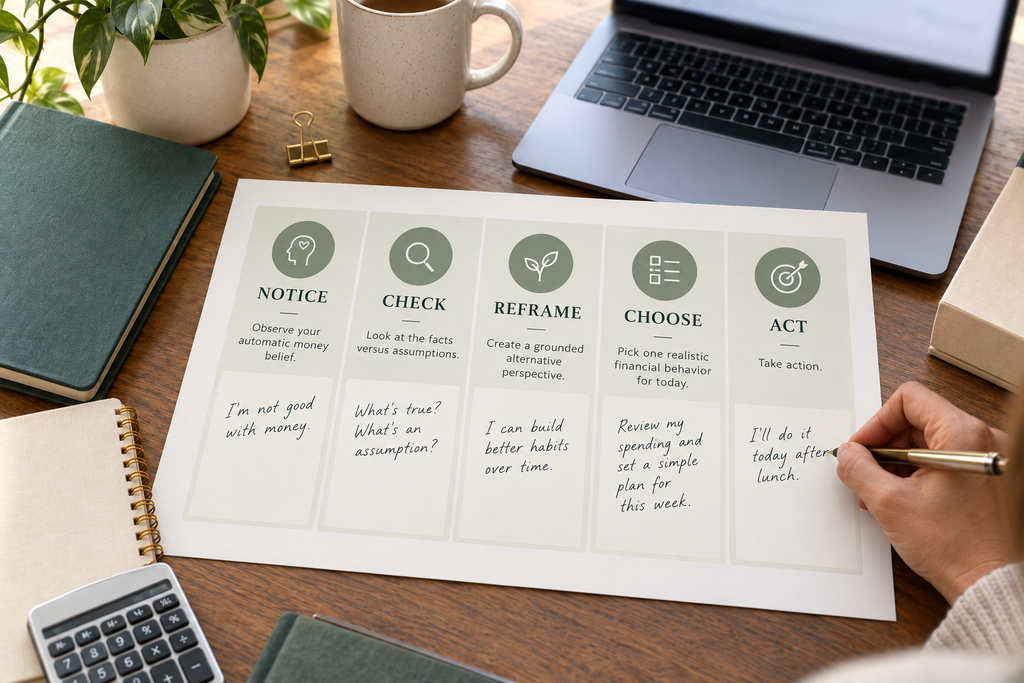
A Simple Five-Step Money-Belief Reset
When an old belief appears, you can work through it in a few minutes.
NOTICE
Write the thought exactly as it appears.
“I am always going to struggle.”
CHECK
Ask which part is fact and which part is prediction.
“My current finances are stressful” may be true. “They will always be this way” is not something you know.
REFRAME
Choose a more grounded statement.
“My finances are difficult right now, and I can still improve specific decisions and systems.”
CHOOSE
Identify one behavior that fits the new perspective.
Review the next seven days of required expenses.
ACT
Complete the smallest useful version immediately or schedule it at a specific time.
This process prevents reflection from ending with a nice sentence. It converts the sentence into behavior.
Do Money Affirmations Help?
Affirmations can be useful when they help interrupt habitual self-criticism or remind you of values, strengths, and intentions. They become less helpful when you expect them to replace real financial action or when the statements are so extreme that you immediately reject them.
Instead of:
“I am instantly wealthy.”
Try:
“I can make one decision today that supports greater financial stability.”
Instead of:
“Money comes to me effortlessly.”
Try:
“I can notice realistic opportunities and develop skills that increase my options.”
Instead of:
“I never worry about money.”
Try:
“I can feel worried and still make a thoughtful financial decision.”
This type of language leaves room for reality while supporting agency.
Replace Shame With Specific Feedback
Shame says:
“I am irresponsible.”
Feedback says:
“I spent more than planned in one category this month.”
Shame says:
“I always fail.”
Feedback says:
“I stopped using my budget after two weeks because the system was too complicated.”
Specific information gives you something to change. Broad condemnation usually does not.
If a financial plan fails, ask why.
Was the goal unrealistic? Did you forget? Did an emergency occur? Was the system confusing? Was the spending trigger emotional? Did you underestimate necessary expenses?
The answer may reveal that you do not need more motivation. You may need a simpler system.
Create a Weekly Money-Mindset Review
Set aside about 10–15 minutes once a week and review both your thoughts and your actions.
Ask yourself:
Which money belief showed up most often?
Identify the sentence rather than using a vague label.
What triggered it?
Look for situations such as comparison, payday, unexpected expenses, work stress, family discussions, or shopping.
What was actually true?
Separate evidence from assumptions.
What did I do differently?
Find one example of a healthier response.
What system would make that response easier next week?
Choose one practical adjustment.
A weekly review prevents the process from becoming endless self-analysis. It gives you a recurring opportunity to move from reflection into planning.
How Structured Mindset Support Can Fit
By this point, you already have a complete free framework: identify the belief, understand its origin, check it against reality, create a grounded alternative, pair it with action, improve your environment, and collect new evidence.
The challenge for some people is consistency. They may understand the process but prefer an organized framework rather than designing every journaling exercise themselves.
A mindset-oriented resource may therefore be useful as optional structure when it supports reflection and consistency without replacing practical financial work. Because the current details of The Wealth Signal could not be verified from the supplied official site, it is important not to assume specific features or results.
If guided structure would make your money-mindset practice easier to maintain, The Wealth Signal may be worth evaluating as an optional complement to your financial routine.
What Mindset Work Cannot Fix by Itself
A healthier money mindset does not erase structural or circumstantial financial problems.
Someone may have strong financial habits and still face unemployment, medical expenses, caregiving costs, unaffordable housing, business setbacks, inflation, or another serious financial shock. The CFPB explicitly notes that some factors affecting financial well-being are within a person’s control and others are not.
This matters because mindset advice becomes unfair when financial hardship is treated as evidence that someone is thinking incorrectly.
A more balanced model is:
Beliefs can influence behavior.
Behavior can influence financial situations.
Circumstances also influence financial situations.
Working on your mindset can improve the part of the process you can influence without pretending you control everything.
A 30-Day Practice for Changing One Money Belief
Instead of trying to rewrite your entire financial identity at once, choose one belief for the next month.
For example:
Old belief: “I cannot save consistently.”
New perspective: “I can practice saving an amount that fits my current circumstances.”
Behavior: Transfer a realistic amount each payday.
Evidence: Record every successful transfer.
Weekly review: Adjust the amount or system if needed.
Another example:
Old belief: “I avoid money because I am bad at finances.”
New perspective: “I can become more capable by looking at my finances regularly.”
Behavior: Complete a 10-minute financial review every Sunday.
Evidence: Record each completed review.
Do not use 30 days as a promise that the belief will disappear permanently. Use it as an experiment that creates enough repetition and evidence to understand what helps you change.
Final Thoughts
Learning how to overcome limiting beliefs about money does not require pretending that every financial difficulty exists only in your mind. It requires becoming more precise about the difference between a real problem and the permanent story you may have attached to it.
Identify the exact belief. Understand where it came from. Separate facts from predictions. Create a grounded replacement perspective and connect it with one financial behavior. Improve your environment, then collect evidence whenever you act differently.
Over time, your new belief becomes less dependent on motivational words because you have real examples behind it.
You may still experience financial fear, make mistakes, or face circumstances outside your control. A healthier mindset does not eliminate those realities; it helps you respond to them with more clarity, skill, and agency.
If The Wealth Signal fits the kind of structured mindset guidance you prefer, decide whether it belongs alongside the practical financial habits you are already building.
What are limiting beliefs about money?
They are beliefs or assumptions that may narrow how someone interprets financial possibilities, abilities, or choices—for example, “I will always struggle” or “I am incapable of managing money.” Financial-socialization research suggests that financial attitudes and behaviors may be shaped partly through family modeling, financial discussions, and experience.
Where do limiting money beliefs come from?
Possible influences include family financial socialization, cultural messages, personal experiences, past financial stress, relationships, and repeated behavior. No single source explains every person’s beliefs, and financial circumstances themselves can strongly influence how someone thinks about money.
Can you completely eliminate a limiting money belief?
It is more useful to focus on noticing the belief sooner and choosing a healthier response than demanding that an unwanted thought never appear again. Repeated new experiences and behaviors can give you evidence that the old belief is no longer the whole story.
Do positive affirmations change money beliefs?
They may support reflection when they are grounded and believable. Research on self-affirmation has found modest psychological benefits, but this research does not show that repeating wealth statements directly causes financial outcomes.
How long does it take to change limiting beliefs about money?
There is no universal timeline. The strength of the belief, how often it is reinforced, your circumstances, and the new experiences you create can all affect the process. Measure progress through changes in awareness, decisions, habits, and financial systems rather than expecting a fixed deadline
Can changing my money mindset make me wealthy?
Mindset alone cannot guarantee wealth. Financial outcomes also depend on income, expenses, debt, opportunities, economic conditions, life events, and other factors, although stronger financial skills, behaviors, and self-efficacy can contribute to financial well-being.