If limiting beliefs about money keep showing up whenever you try to save, earn more, make a financial plan, or think about your future, the problem may feel deeply personal. You might tell yourself that you are simply “bad with money,” that financial security is for other people, or that one past mistake proves you cannot change. These thoughts can influence behavior, but they are not the same thing as permanent facts.
Money attitudes do not develop in a vacuum. Research on financial socialization has examined how parental modeling, money discussions, and firsthand financial experiences can relate to later financial attitudes, knowledge, and behavior. The Consumer Financial Protection Bureau also notes that financial habits and norms involve values, attitudes, emotions, social expectations, and contextual cues that can influence everyday money decisions.
That does not mean mindset determines everything. Income, debt, employment, health expenses, housing costs, family responsibilities, economic conditions, and access to opportunities all affect financial outcomes. A useful money-mindset practice does not pretend those realities disappear; it helps you separate an automatic belief from the next decision you can actually influence.
Healthy money mindset → practical ways to build a healthier relationship with money
What Are limiting beliefs about money?
A limiting money belief is a thought or assumption that narrows what you believe is possible, appropriate, or manageable around finances. Examples include “I will never be good at saving,” “Money always disappears,” “People with money are selfish,” or “I have already made too many financial mistakes to recover.”
Some beliefs may come from messages you observed or heard growing up, while others can form through stressful experiences, social comparison, financial setbacks, or repeated habits. Research on financial socialization supports the broader idea that family modeling, conversations, and experiential learning can influence financial attitudes and behavior later in life.
The goal is not to search for one hidden belief and blame it for every financial difficulty. A healthier approach is to identify thoughts that repeatedly affect your choices, check them against current reality, and develop a more useful response.
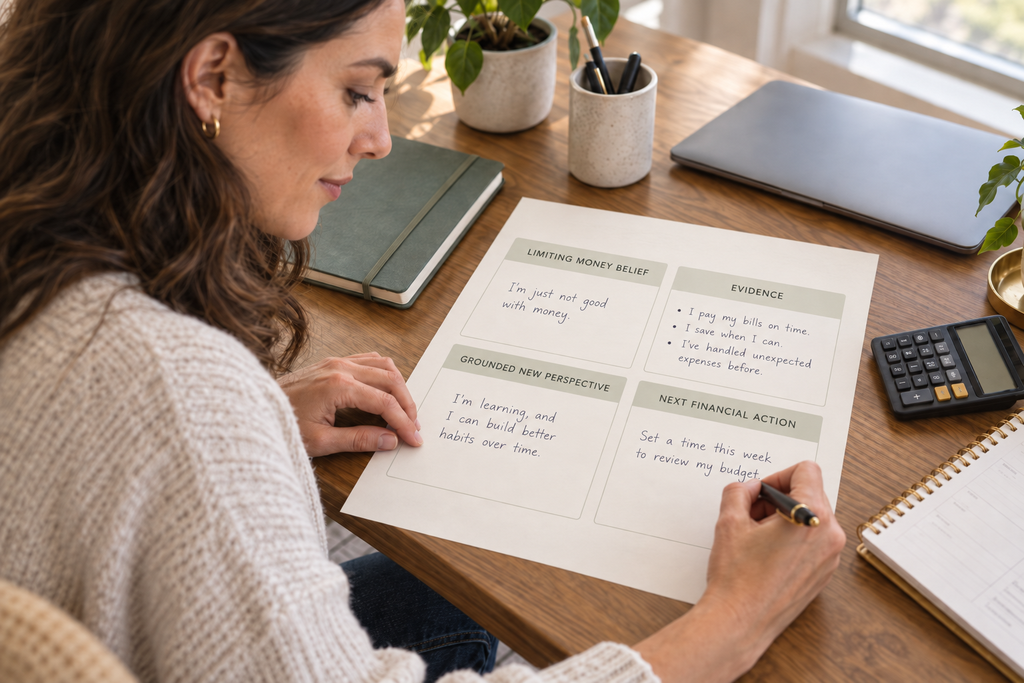
A simple framework is:
Old belief → evidence → grounded perspective → next financial action
That final step matters because mindset change becomes more meaningful when it changes what you actually do.
Why Money Beliefs Can Affect Financial Behavior
Thoughts about money can influence whether you look at your finances or avoid them, whether you save after getting paid or postpone it, whether you negotiate, whether you seek information, and how you respond after a mistake. A 2024 scoping review of money-management research identified financial beliefs and knowledge, attitudes, self-efficacy, affective responses, and social influences among potential correlates of money-management behavior, while also noting that the research base is heterogeneous and does not support simplistic conclusions.
The CFPB similarly describes financial habits and norms as patterns that guide everyday financial choices. It also emphasizes that financial well-being involves more than income alone: having control over current finances, being able to absorb financial shocks, progressing toward goals, and having greater freedom of choice all matter.
This gives you a useful standard for evaluating mindset work. A new belief is valuable when it helps you make clearer decisions, build useful habits, or engage more confidently with your actual financial situation.
The following seven patterns are common examples worth examining.
1. “I Will Always Struggle With Money”
This belief turns a current situation into a permanent identity. You may genuinely be dealing with debt, inconsistent income, high expenses, or limited savings, but “things are difficult right now” is different from “things can never improve.”
A more grounded perspective is:
“My current financial situation is real, but it does not tell me every decision or opportunity available in the future.”
That statement does not require unrealistic optimism. It simply stops turning today’s numbers into a prediction about your entire life.
Then connect the new belief to one action. Review one bill, identify one expense, calculate what a savings goal would require, or research one realistic way to improve income. The purpose is to create evidence that you can interact with the problem instead of treating it as untouchable.
Quick reflection
Write down:
What is difficult right now?
What am I predicting because of it?
Which part of that prediction is not actually known?
What is one thing I can influence this week?
That distinction between present facts and permanent predictions is one of the most useful places to begin.
2. “I Am Bad With Money”
“I am bad with money” sounds like a description, but it is usually too broad to be useful. Maybe you overspend in one category, find investing confusing, forget due dates, or struggle to save consistently. Those are specific behaviors or skill gaps—not proof that your identity is financially defective.
Replace the label with a narrower statement:
“There are financial skills and habits I have not mastered yet.”
That wording opens the door to learning. Budgeting can be practiced. Automatic payments can reduce missed due dates. Spending triggers can be identified. Financial concepts can be learned gradually.
The CFPB’s financial education framework emphasizes that people differ in their circumstances, goals, and environments and that improving financial behavior requires more than giving everyone the same piece of advice.
Your next question becomes much more productive: Which specific money skill would improve my life most right now?
3. “Wanting More Money Makes Me Greedy”
For some people, wanting financial growth creates guilt. Money may have become associated with selfishness, materialism, conflict, or people behaving badly. If that association is strong, you can consciously want greater financial security while emotionally resisting the idea of having more.
A more balanced belief separates money from character:
“Having more financial resources does not decide what kind of person I become; my values influence how I use those resources.”
More money could mean more choices, a stronger emergency cushion, less dependence on debt, education, supporting family, charitable giving, or simply having greater control over everyday life. The CFPB’s definition of financial well-being emphasizes both security and freedom of choice rather than a particular income or net-worth target.
When examining limiting beliefs about money, this distinction can be important. You do not need to worship money to want greater financial stability. You can pursue financial improvement while keeping generosity, relationships, ethics, health, and other personal values intact.
4. “There Is Never Enough”
This belief often appears as scarcity thinking: not enough money, not enough time, not enough opportunities, or no room for a mistake. Sometimes the scarcity is objectively real. If income does not cover necessary expenses, telling yourself to “think abundant thoughts” does not solve the financial gap.
The useful shift is not “There is always unlimited money.” It is:
“I can acknowledge what is limited while still looking for the resources, choices, and next steps that remain available.”
Suppose your budget is genuinely tight. Available options may still include identifying the highest-priority expense, negotiating a bill, changing the timing of a payment, finding assistance, reviewing subscriptions, increasing work hours where feasible, developing an income-producing skill, or seeking qualified financial guidance.
Grounded abundance thinking widens attention without denying constraints. It asks, “Given what is true, what is still possible?”
Where The Wealth Signal May Fit
Some people prefer to work through money beliefs independently using journaling, reflection, and practical financial exercises. Others find it easier to maintain mindset work when they have a structured resource to follow.
That is where The Wealth Signal may have relevance as optional mindset-oriented support. The supplied official sales-page URL could not be reliably fetched during research, so current information about the product’s creator, format, modules, audio components, pricing, bonuses, guarantee, or claimed results cannot be responsibly confirmed here.
For that reason, it should not be presented as a substitute for budgeting, saving, financial education, income planning, or other real-world financial decisions.
If you want structured mindset support alongside practical money habits, consider whether The Wealth Signal fits the kind of routine you prefer.
5. “If I Cannot Make Big Progress, Small Steps Are Pointless”
Large financial goals can make modest actions look insignificant. If you want a $20,000 emergency fund, saving $25 may seem meaningless. If you want to eliminate substantial debt, one small extra payment can feel almost invisible.
But financial systems are often built through repeated behavior rather than dramatic individual moments. The CFPB encourages people to break financial goals into concrete steps and build systems that make those steps easier to repeat, such as scheduled reminders or automatic transfers.
A more useful belief is:
“Small actions matter when they become part of a repeatable system.”
The point is not that $25 magically becomes wealth. The point is that a repeatable savings behavior can create a foundation that may later scale when circumstances improve.
Try replacing “Is this amount impressive?” with:
“Can I repeat this action consistently?”
That question shifts attention from appearance to process.
6. “More Income Will Fix Every Money Problem”
Increasing income can make an enormous difference, especially when basic expenses already consume most of what someone earns. It would be misleading to pretend every financial challenge can be solved purely through budgeting or mindset.
At the same time, more income does not automatically create strong financial systems. If spending rises with every income increase, goals remain undefined, bills stay disorganized, or savings continually get postponed, greater earnings may not create the security you expected.
A balanced belief is:
“Income matters, and how I manage available resources matters too.”
This allows you to work on two paths at once. One path focuses on earning capacity—skills, career development, negotiation, business, or other realistic opportunities. The other focuses on financial systems—planning, saving, debt management, spending decisions, and financial organization.
CFPB research on saving habits has found an association between regular saving and better measures of financial security, while also emphasizing that financial strain is shaped by circumstances such as financial shocks and difficulties paying bills.
That is a more realistic model than either “income does not matter” or “income solves everything.”
Financial abundance mindset → how to combine abundance thinking with practical financial action
7. “My Past Financial Mistakes Prove I Cannot Change”
Past mistakes can be expensive, embarrassing, and emotionally difficult. A bad investment, debt, overspending, missed payments, or a business decision that failed can stay in your mind long after the event itself.
The problem begins when a past behavior becomes a permanent identity:
“I made a bad financial decision” becomes “I cannot make good financial decisions.”
A more useful perspective is:
“My past decisions contain information I can use when making the next one.”
Ask what actually went wrong. Did you lack information? Act under pressure? Ignore a warning sign? Spend emotionally? Take more risk than you understood? Have no emergency reserve? Assume future income would arrive?
Specific lessons are actionable. Shame is usually much less specific.
When working through limiting beliefs about money, the goal is not to erase your history. It is to stop requiring your future to repeat it.
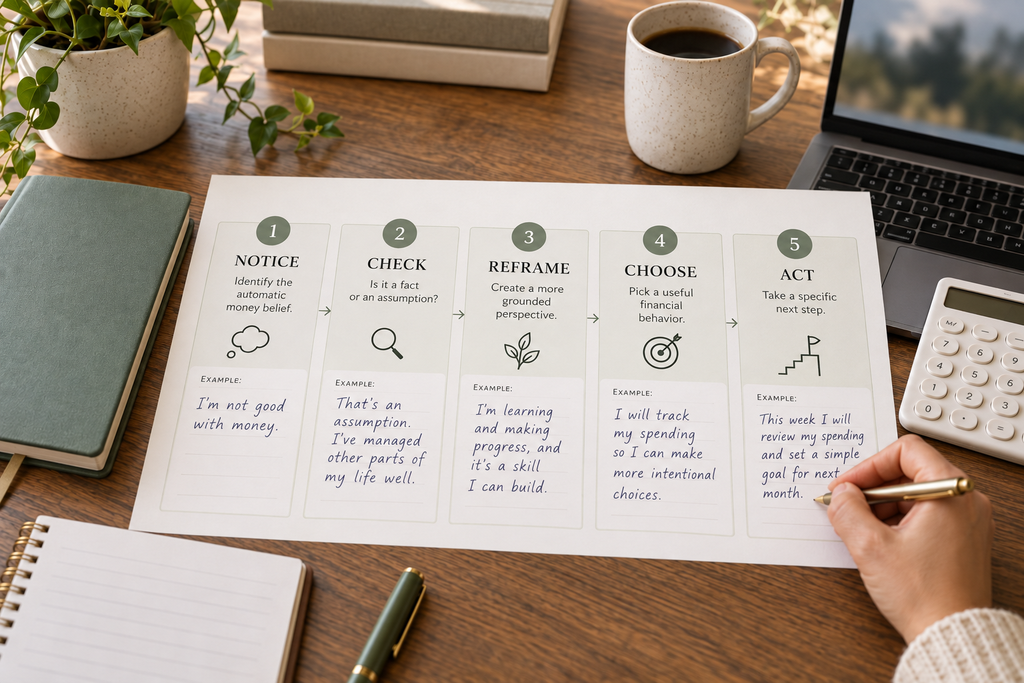
A Five-Step Exercise for Changing a Money Belief
Use this exercise whenever an automatic financial thought appears strongly:
- NOTICE — Write the belief exactly as it appears.
- CHECK — Separate current facts from assumptions or permanent predictions.
- REFRAME — Create a more balanced perspective you can genuinely believe.
- CHOOSE — Identify one behavior that supports the new perspective.
- ACT — Complete the smallest realistic version of that behavior.
For example:
Notice: “I can never save money.”
Check: “Saving has been inconsistent, but ‘never’ is not accurate.”
Reframe: “I can practice saving smaller amounts consistently.”
Choose: “Transfer a manageable amount after payday.”
Act: “Schedule the first transfer.”
This is also a practical way to use affirmations. Rather than repeating “I am wealthy” while feeling disconnected from the statement, choose language that supports the behavior you actually want.
Research summarized by the American Psychological Association suggests that self-affirmation interventions—typically involving reflection on personal values, identity, or positive personal qualities—can produce small improvements in several well-being outcomes. That evidence does not establish that repeating wealth statements creates financial outcomes, but it supports treating thoughtful self-reflection differently from magical financial promises.
Build Evidence for the New Belief
Changing a belief becomes easier when you collect examples that contradict the old one.
If your old belief is “I am financially irresponsible,” notice moments when you behave responsibly:
- you review an account instead of avoiding it;
- you question an unnecessary purchase;
- you pay a bill on time;
- you ask for information before making a decision;
- you save even a modest amount;
- you learn a new financial concept;
- you notice a spending trigger;
- you make a realistic plan after a setback.
One example does not erase years of habit, but repeated evidence can make your new perspective increasingly believable.
Keep a short money-belief journal with four fields:
Belief noticed
Trigger
Better response
Small evidence
After several weeks, look for patterns. You may discover that certain situations—stress, comparison, payday, family conversations, social media, or unexpected expenses—activate specific beliefs more often than others.
Create Financial Systems That Support the New Mindset
Thought work becomes much stronger when your environment reinforces it.
If your new belief is “I can become a consistent saver,” create a savings system. If it is “I can face my finances calmly,” schedule a weekly financial check-in. If it is “I can make more intentional purchases,” create a waiting rule before buying nonessential items.
The CFPB encourages consumers to turn goals into concrete steps and create personal financial rules that fit their circumstances. Its guidance emphasizes that financial advice needs to work with the person’s actual situation rather than an idealized one.
This is where mindset becomes visible.
A thought such as “I am becoming more intentional with money” is useful only if it eventually shows up as a decision, habit, boundary, plan, or system.
Weekly money mindset routine → simple weekly money reflection and planning routine
A Weekly Money-Belief Review
Once a week, spend about 10 minutes reviewing the way you thought and acted around money.
Ask:
Which belief appeared most often?
Maybe it was “There is never enough” or “I am already too far behind.”
What triggered it?
A bill, comparison, purchase, work situation, or financial conversation may reveal a pattern.
What was actually true?
Separate the situation from the story that appeared around it.
What did I do differently?
Look for behavioral evidence.
What system could help next week?
A reminder, automatic transfer, spending rule, calendar block, or clearer goal may reduce how often you have to rely on motivation.
This approach turns limiting beliefs about money into something you can observe and work with rather than an invisible force controlling your financial life.
When Structured Mindset Guidance May Help
You can complete all of the exercises above independently. A notebook, honest reflection, practical financial information, and consistent action may be enough for many people.
Other people prefer guided material because structure makes it easier to maintain a routine. The important question is not whether a paid mindset resource can guarantee wealth; it is whether structured reflection helps you practice useful changes consistently.
The Wealth Signal can therefore be evaluated as an optional complement to the free belief-to-action approach described here, provided that its current presentation matches the type of mindset support you want and your expectations remain realistic.
If guided reflection would help you practice these shifts more consistently, evaluate whether The Wealth Signal suits the way you prefer to work on your money mindset.
What Money Mindset Work Cannot Do
Mindset work can influence your interpretation of events and the choices you make, but it cannot control every factor affecting your finances.
Someone may have excellent financial habits and still face a medical expense, job loss, caregiving burden, business downturn, housing problem, or other financial shock. CFPB guidance explicitly recognizes that financial well-being is shaped by multiple factors and that some are within a person’s control while others are not.
That matters because money-mindset content can become harmful when every financial difficulty is interpreted as evidence of “negative energy,” weak manifestation, or incorrect thoughts.
A responsible approach is more balanced:
Your beliefs matter because they can affect behavior. Your circumstances matter because they affect what options are realistically available.
Both can be true at the same time.
Final Thoughts
Understanding limiting beliefs about money is not about blaming yourself for every financial challenge or pretending that positive thoughts produce guaranteed wealth. It is about noticing the stories that repeatedly shape your choices and deciding whether those stories still deserve authority over your next action.
Start with one belief rather than trying to transform your entire relationship with money overnight. Write down what you automatically think, check it against reality, create a grounded alternative, and connect that alternative with one practical behavior.
Then collect evidence.
One better decision will not rewrite your financial life immediately, but it can become part of a different pattern. Repeated decisions, clearer goals, useful systems, better information, and greater self-awareness can gradually create a healthier relationship with money.
If The Wealth Signal matches the kind of structured mindset support you want, decide whether it belongs alongside—not instead of—the practical financial habits you are building.
Are limiting money beliefs real?
People can hold attitudes and beliefs about money that relate to financial behavior. Research on financial socialization and money-management behavior has examined links among financial attitudes, beliefs, self-efficacy, social influences, and financial behaviors, although these relationships are complex and should not be reduced to the idea that beliefs alone determine outcomes.
Where do negative money beliefs come from?
They may develop through family financial socialization, observed behavior, money conversations, firsthand experiences, cultural messages, and later financial events. Research reviews identify parental modeling, parent-child financial discussion, and experiential learning as important parts of financial socialization.
How do I identify an unhealthy money belief?
Listen for absolute statements such as “I always,” “I never,” “people like me cannot,” or “there is no point.” Then ask whether the statement describes a specific current reality or makes a much broader prediction about your identity and future.
Can affirmations change money beliefs?
Affirmations may support reflection when the statements are believable and connected to personal values or constructive behavior. Research summarized by the APA has found modest well-being benefits from self-affirmation interventions, but this does not demonstrate that repeating financial statements directly creates money.
How long does it take to change a money belief?
There is no fixed timeline. Beliefs that have been reinforced for years may require repeated awareness, new experiences, and consistent behavior before a different perspective feels natural. It is more useful to track changes in decisions and habits than to expect a specific deadline.
Does changing your money mindset make you wealthy?
Not by itself. Mindset can influence behavior, but financial outcomes are also affected by income, expenses, debt, opportunity, economic conditions, life events, and many other factors. Practical financial action remains essential.