Using money manifestation journal prompts can help turn vague wishes about abundance into something you can actually examine. Instead of writing only “I want more money,” you can explore what financial security means to you, which beliefs affect your decisions, what resources you already have, what obstacles keep appearing, and what action could move you forward. You can keep manifestation as a spiritual or personal-growth practice while staying grounded in financial reality.
Journaling is not a scientifically established method for attracting money, and writing a desired outcome does not guarantee that it will happen. Research on positive expressive writing does, however, suggest that some writing practices—such as gratitude and “best possible self” exercises—may support well-being and positive affect, although a 2025 systematic review rated the included studies as generally poor or fair quality and found less consistent effects for some outcomes.
That makes journaling most useful as a reflection and planning tool rather than a substitute for financial action. The prompts below are designed to help you move from wish → awareness → perspective → plan → action.
How to use money manifestation journal prompts in a grounded way
You do not need to answer every question in one sitting. Choose three to five prompts that match what you are dealing with right now, write without trying to sound impressive, and pay attention to repeated beliefs or themes. A useful journal entry should leave you with greater clarity rather than pressure to prove that you are “positive enough.”
It also helps to distinguish a desired financial future from the belief that thinking about it will automatically create it. Research on manifestation beliefs found that stronger endorsement of manifestation was associated with greater perceived success and aspirations, but also with greater attraction to risky investments, reported bankruptcy, and stronger belief in achieving unlikely success quickly. The study was correlational, so it does not establish that manifestation beliefs caused those outcomes.
A grounded practice can keep the hopeful part—clarity, imagination, motivation, reflection—while adding evidence, realistic goals, and follow-through.
Below are exactly 33 prompts, organized so that you can move from understanding your current money relationship toward concrete action.
1. Start With Your Current Relationship With Money
Before visualizing wealth, identify what money means to you today. Your answers may reveal that the goal behind “more money” is actually safety, flexibility, independence, relief, opportunity, or the ability to support people you care about.
1. What does “enough money” mean in my real life—not in comparison with anyone else?
2. Which financial situation currently takes up the most mental energy for me?
3. When I think about becoming more financially secure, what emotion appears first?
4. What would greater financial stability allow me to do, choose, or stop worrying about?
5. Which part of my financial life do I feel most confident about right now?
6. Which part of my financial life do I tend to avoid, and what makes it uncomfortable to face?
The CFPB defines financial well-being as having financial security and freedom of choice, including control over everyday finances, the ability to absorb a financial shock, progress toward goals, and freedom to make choices that support your life. That can be a more useful definition of abundance than simply imagining an arbitrary income or bank-balance number.
Quick takeaway
If your answer to “What do I want?” is vague, keep asking “What would that change for me?” until the goal becomes specific enough to understand.
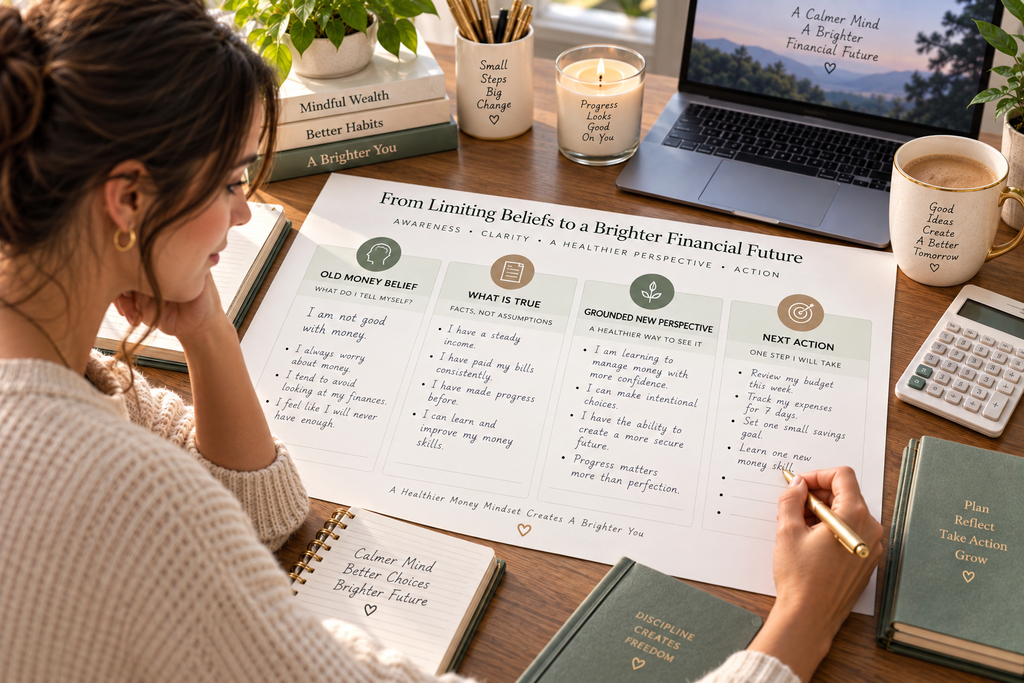
2. Explore Your Money Beliefs
Many people carry money rules that feel like facts because they have heard or repeated them for years. Journaling gives you a place to notice those rules without immediately accepting or rejecting them.
7. What sentence about money did I hear repeatedly while growing up?
8. Which belief about wealthy people do I currently hold, and where might that belief have come from?
9. What do I believe I must sacrifice in order to earn more money?
10. When I make a financial mistake, what do I automatically tell myself about who I am?
11. Which money belief feels permanent but may actually be a prediction rather than a fact?
12. What would be a more balanced, believable version of that belief?
For example, “I am terrible with money” might become “I have made mistakes, but financial skills can be learned and practiced.” “Money always disappears” might become “I can create systems that give part of my money a purpose before I spend it.”
This is where money manifestation journal prompts can become more practical than generic affirmations. Instead of forcing yourself to write “I am wealthy,” you identify the thought that is actually influencing your choices and develop a perspective you can connect with behavior.
Where The Wealth Signal May Fit
You can do all of this belief work independently with a notebook. Some people, however, prefer using structured mindset material because a defined framework can make reflection easier to repeat consistently.
That is the most appropriate context for The Wealth Signal here. The supplied official sales page could not be reliably accessed during research, so current details about its creator, exact format, modules, audio material, exercises, bonuses, pricing, guarantee, or financial outcome claims cannot be responsibly verified.
Because those specifics are unavailable, the product is best viewed as optional mindset-oriented support rather than proof of a particular wealth or manifestation mechanism.
If structured abundance-focused guidance would help you stay consistent with mindset work, consider whether The Wealth Signal fits alongside the practical financial habits you are already building.
3. Define What Abundance Actually Means to You
“Abundance” becomes much easier to work with when you translate it into experiences, choices, and goals.
13. If I felt financially secure, what would an ordinary Tuesday look like differently?
14. Which form of abundance matters most to me right now: stability, time, flexibility, opportunity, generosity, or something else?
15. What financial goal would genuinely improve my life rather than simply impress other people?
16. Which part of my vision is within my influence, and which part depends on circumstances I cannot fully control?
17. What would meaningful financial progress look like during the next 90 days?
These questions are intentionally less glamorous than imagining unlimited riches. Financial well-being is shaped by both behavior and circumstances, and the CFPB notes that some factors affecting financial well-being are within a person’s control while others are not.
A grounded abundance journal makes room for both truths: you can influence your choices without assuming you control every outcome.
4. Use Visualization Prompts That Include the Process
Visualization can help you make an abstract future feel more concrete, but the imagined scene becomes more useful when it includes the process behind the goal.
18. What financial future do I want to picture clearly, and why does it matter emotionally?
19. What repeated behavior would probably exist in that future?
20. If I could watch my future self handle money for one week, what would I see them doing differently?
21. What obstacle in my current life makes that behavior difficult?
22. What realistic bridge could connect today’s situation with the future I am visualizing?
Research on mental contrasting offers a useful model here. It combines imagining a desired future with identifying the present obstacle that stands in the way, and a meta-analysis of 21 studies involving 15,907 participants found a small-to-medium positive effect when mental contrasting was combined with implementation intentions for goal attainment.
So when using money manifestation journal prompts, do not stop after describing the dream. Add the obstacle and the bridge.
Example:
Desired future: I have a stronger emergency fund.
Present obstacle: I usually wait until the end of the month to save what remains.
Realistic bridge: Decide on a manageable amount and move it shortly after income arrives.
That structure keeps visualization connected with behavior.
5. Use Gratitude to Identify Resources
Gratitude does not require pretending that every financial circumstance is good. Use it to notice useful resources that may be easy to overlook when your attention is focused only on what is missing.
23. What financial progress, however small, can I acknowledge today?
24. Which skill, relationship, opportunity, or resource already supports my financial life?
25. What money lesson am I grateful to understand now that I did not understand earlier?
26. What resource am I underusing at the moment?
27. How could I put one existing resource to better use this week?
A 2025 review of positive expressive-writing interventions found comparatively consistent well-being benefits for practices such as gratitude writing and “best possible self” exercises, while also noting important limitations in the quality of the evidence.
That is a reasonable way to frame gratitude journaling: it may support reflection and positive perspective, but it is not evidence that gratitude itself causes wealth to appear.
6. Turn Your Journal Into Financial Action
A useful manifestation journal should eventually leave the page.
These final prompts move from intention to behavior.
28. What is the single most useful financial action I could take within the next 24 hours?
29. What small task am I avoiding because I have made it feel larger than it really is?
30. What action would provide evidence for the money belief I want to strengthen?
31. What specific situation usually triggers an unhelpful financial behavior, and what could I do instead?
32. What “if-then” plan could make my next step easier to follow?
33. One week from now, what completed action would make me glad I used this journal today?
For prompt 32, use a structure such as:
If payday arrives, then I will complete my planned savings transfer.
If I want to make an unplanned purchase above my personal limit, then I will wait 24 hours before deciding.
If I begin avoiding my weekly money review, then I will commit to reviewing only the next seven days.
Implementation intentions are specific if-then plans that link a situation with a predetermined behavior. Research has repeatedly studied them as a self-regulation strategy for helping translate goals into action.
A Simple 10-Minute Manifestation Journaling Routine
You do not need to complete all 33 prompts every day. A shorter routine can make the practice easier to maintain.
Minutes 1–2: Name the financial intention
Write one sentence:
“The financial outcome I want to move toward is __________.”
Make it concrete enough to understand.
Minutes 3–4: Notice the current belief
Choose one question from prompts 7–12 and write without editing yourself.
For example:
“The belief appearing today is: small savings amounts do not matter.”
Minutes 5–6: Visualize and contrast
Picture your desired future, then answer:
“What is the main obstacle between that future and today?”
Minutes 7–8: Identify a resource
Write one thing you already have that could support progress.
Perhaps it is time, a skill, an existing savings habit, information, professional experience, or someone who can provide appropriate guidance.
Minutes 9–10: Choose one action
Finish with:
“Within the next 24 hours, I will __________.”
That final line prevents the routine from ending with intention alone.
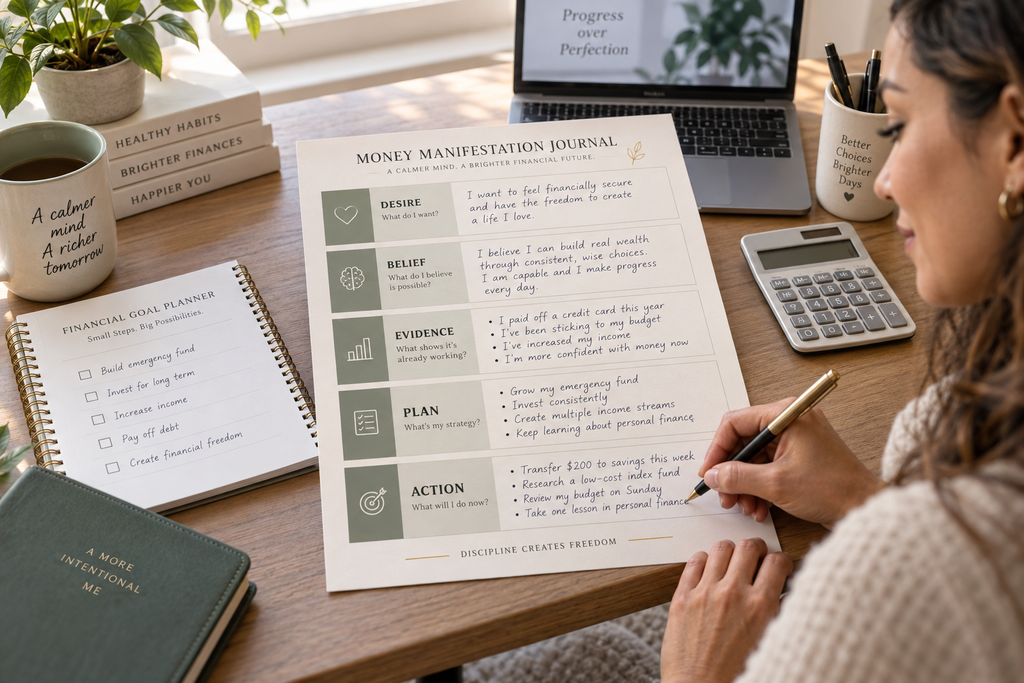
Create a Five-Part Money Manifestation Journal Page
If you prefer a repeatable template, divide each page into five sections:
1. DESIRED FINANCIAL FUTURE
What am I working toward?
2. CURRENT MONEY BELIEF
What thought or assumption appeared today?
3. WHAT IS TRUE
What facts do I actually know?
4. GROUNDED NEW PERSPECTIVE
What interpretation is more useful without denying reality?
5. NEXT FINANCIAL ACTION
What will I do?
Example:
Desired future: Build emergency savings.
Current belief: “I never save consistently.”
What is true: “My saving has been inconsistent during the last few months.”
Grounded perspective: “Inconsistency does not prevent me from creating a simpler system.”
Next action: “Choose a realistic automatic transfer amount.”
This structure makes money manifestation journal prompts useful even on days when you do not feel particularly inspired.
Avoid the “Perfect Positive Entry” Trap
Your journal is not a test of whether you have the right vibration.
If you are worried, write that you are worried. If you feel frustrated about debt, acknowledge the frustration. If you are uncertain about an opportunity, allow the uncertainty to appear on the page.
The point is not to erase every negative thought. It is to examine whether that thought contains useful information, an exaggerated prediction, or a behavior you can change.
For example:
“I am afraid I will never catch up.”
might become:
“My current progress feels slower than I want. What is one financial priority that would improve my position first?”
That question creates somewhere to go next.
Do Not Use Journaling Instead of Financial Information
There are times when reflection is useful and times when you simply need the numbers.
If you are worried about spending, review the spending. If you are concerned about debt, understand the balance, terms, and payment requirements. If you are considering an investment, evaluate its risks and evidence rather than relying on how “aligned” it feels.
The manifestation-belief research discussed earlier is relevant here because greater belief in manifestation was associated with greater attraction to risky investments and expectations of reaching unlikely success more quickly. Again, that association does not prove causation, but it is a reason to pair optimism with careful financial judgment.
Your journal can help you ask better questions. It should not make facts optional.
When Structured Mindset Support May Help
At this point, you already have a complete self-directed journaling system: 33 prompts, a 10-minute routine, a five-part template, and a method for turning visualization into an action plan. You do not need a paid resource for the article to be useful.
Some people still prefer more external structure because deciding what to reflect on every day can become another task. An organized mindset framework may appeal to readers who enjoy following a defined routine rather than creating one from scratch.
Specific features of The Wealth Signal should not be assumed because its supplied official page was not reliably accessible during research.
If you prefer an organized mindset framework instead of building every journaling exercise yourself, The Wealth Signal may be worth evaluating as optional support alongside your financial goals.
Try a Weekly Money Manifestation Review
Once a week, review what your journal is showing you.
Do not reread every page searching for “signs.” Look for patterns.
Ask:
- Which money belief appeared most often?
- Which goal remained most important?
- Which obstacle kept showing up?
- Which financial action did I actually complete?
- Which action did I repeatedly postpone?
- Which resource did I overlook?
- Which affirmation or perspective felt genuinely useful?
- What does next week need to be simpler?
Then choose one focus for the next seven days.
For example:
Belief: “Small progress does not count.”
Weekly focus: Track every completed financial action, however small.
Behavior: Make the planned savings transfer after payday.
This creates continuity between your entries.
A 30-Day Journal Experiment
If you enjoy this style of reflection, try it for 30 days as an experiment rather than a guaranteed manifestation timeline.
Each day, choose three prompts: one about belief, one about the desired future, and one about action. Keep the entries brief enough that the routine does not become difficult to maintain.
At the end of the month, review your journal and ask:
Have I become clearer about what financial abundance means to me?
Am I identifying unhelpful money thoughts sooner?
Do I understand my recurring obstacles better?
Have I completed more concrete financial actions?
Which habits or systems need continued work?
Has my relationship with uncertainty changed?
The answers give you a more meaningful measure than asking whether the universe “delivered” within 30 days.
Deciding Whether External Guidance Fits Your Routine
Before adding a structured mindset resource, identify the gap you actually want it to fill.
If you already enjoy writing independently, you may need nothing more than a consistent schedule. If you repeatedly abandon the routine because you do not know what to focus on, more structure may be useful. If the real problem is a specific financial challenge, a mindset resource may be less important than appropriate financial, legal, tax, or other professional guidance.
The supplied product page did not provide accessible information that could be verified here, so decisions about The Wealth Signal should be based on current product information available to you rather than assumptions about its contents.
Final Thoughts
The strongest money manifestation journal prompts do not ask you to choose between hope and reality. They help you clarify what you want, understand the beliefs shaping your relationship with money, picture the future more deliberately, appreciate resources you already have, identify obstacles, and decide what you can do next.
Use the 33 questions as a library rather than a checklist you must complete every day. Some entries may focus on gratitude, others on fear, planning, visualization, or financial behavior. What matters is whether the practice gradually creates greater clarity and better follow-through.
A grounded journaling sequence is:
DESIRE → BELIEF → REALITY → PERSPECTIVE → PLAN → ACTION
Your journal can hold the vision. Your decisions still build the bridge.
If The Wealth Signal matches the structured abundance approach you prefer, decide whether it belongs alongside—not instead of—the practical financial habits supporting your goals.
What are money manifestation journal prompts?
They are questions designed to help you reflect on financial goals, beliefs, abundance, gratitude, visualization, and action. A grounded approach uses them for clarity and planning rather than assuming that journaling itself guarantees money.
How many manifestation prompts should I answer each day?
There is no required number. Three to five focused questions are often easier to answer thoughtfully than trying to complete a long list every day.
Can manifestation journaling attract money?
There is no established scientific evidence that writing about wealth directly attracts financial outcomes. Journaling can instead be used to clarify goals, examine beliefs, and plan behavior.
Does gratitude journaling help?
A 2025 systematic review of positive expressive-writing interventions found relatively consistent benefits for well-being and positive affect from approaches including gratitude and best-possible-self writing, although the overall study quality was rated poor or fair.
What should I write if positive affirmations feel fake?
Write a bridge statement. Instead of “I am already rich,” try something such as “I can strengthen my financial position through realistic choices and consistent habits.”
Should manifestation journaling replace financial planning?
No. Financial well-being involves everyday financial control, resilience to financial shocks, progress toward goals, and freedom of choice, so practical financial behavior remains important.