If you are exploring subconscious reprogramming for abundance, you are probably not looking for another vague message to “just think positive.” You may already understand what you want—more financial stability, confidence, opportunity, or a less anxious relationship with money—but still notice automatic thoughts such as “there is never enough,” “I always mess this up,” or “people like me do not get ahead.” The useful goal is not to pretend those thoughts never exist. It is to notice them, question them, and repeatedly connect a more helpful mindset with practical behavior.
This guide treats abundance as a mindset-and-action practice rather than a guarantee. You will learn a seven-step routine using awareness, reframing, visualization, journaling, repetition, and practical financial action.
Quick Takeaway: The most grounded version of this practice is not “repeat a phrase until wealth arrives.” It is “change the mental pattern, then give the new pattern a behavior to guide.”
What Subconscious Reprogramming for Abundance Actually Means
The phrase “subconscious reprogramming” is common in spirituality and self-help, but it is not one standardized scientific technique. A practical interpretation is to focus on the beliefs, emotional reactions, attention habits, and routines that shape how you respond to money. Some may feel automatic because they have been repeated for years.
Habit research supports the broader idea that repeated responses in recurring contexts can become more automatic over time. A major review of habit psychology describes habits as efficient default responses that develop through repetition and interact with deliberate goal pursuit. That does not prove that affirmations can “program” the subconscious for wealth, but it does give you a grounded reason to pair repeated mindset work with repeated behavior.
This distinction lets you use journaling, visualization, affirmations, or meditation as tools for attention and reflection without treating metaphysical claims as established facts. Pair them with budgeting, skill building, applications, negotiation, saving, or business improvement.
Abundance mindset exercises → practical exercises for developing a healthier relationship with money
Step 1: Identify the Automatic Money Story You Keep Repeating
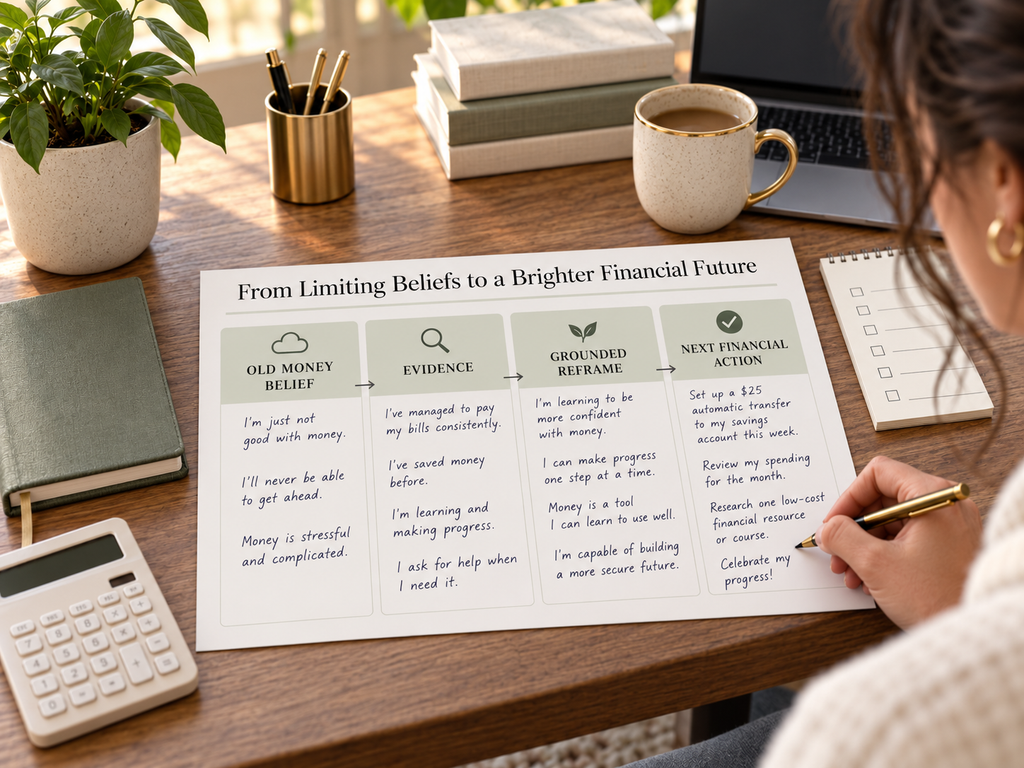
Start by noticing the sentence that appears automatically when money becomes emotionally charged. It may show up when you check your bank balance, see someone else’s success, consider charging more for your work, think about debt, or imagine a larger financial goal. Write the sentence exactly as it appears instead of cleaning it up.
Common examples include “I will never catch up,” “money always disappears,” “I am bad with money,” “earning more is for other people,” or “if I become successful, people will judge me.” The purpose is not to shame yourself for having the belief. You are trying to turn an invisible pattern into something specific enough to examine.
Then add two notes: When does this thought appear? and What do I usually do next? You may discover that the belief is tied to avoidance, impulsive spending, procrastination, underpricing, or giving up before taking a useful step.
Practical Exercise: For one week, keep a “money belief log” with four lines: Trigger → Automatic thought → Emotion → Action. Patterns are much easier to change once you can see the sequence.
Step 2: Replace Extreme Positivity With a Believable New Perspective
Many people make abundance affirmations so positive that their own mind immediately rejects them. If you are worried about bills, repeating “I am effortlessly wealthy beyond measure” may create more internal resistance than confidence. A better reframe feels hopeful but believable enough that you can act from it.
For example, replace “I always fail with money” with “I can learn one financial skill at a time.” Replace “there is never enough” with “I can focus on what I can improve, protect, and build from here.” Replace “I need a miracle” with “small financial actions can compound when I repeat them.”
This is where the practice becomes more useful. The new statement is not a prediction about the universe; it is a mental instruction that helps you respond differently when the old belief appears. Your reframe should make the next useful action easier, not make reality disappear.
Step 3: Use Visualization to Rehearse Behavior, Not Just Outcomes
Visualization can become unhelpful when it stops at the fantasy of having more money. A stronger practice is to visualize the behavior of the person you want to become. Imagine opening your accounts calmly, asking a client a clear question, applying for a role, transferring money to savings, finishing a course, or having a direct conversation about compensation.
Keep the scene specific. What decision are you making, what discomfort appears, and how do you respond? The goal is not to “feel rich” and return to the same habits. It is to rehearse a more capable response to a real situation.
Research on mental contrasting with implementation intentions is useful here because it pairs a desired future with the obstacle in the present and then creates an if-then plan. A 2021 meta-analysis covering 21 studies and 15,907 participants found a small-to-medium positive effect on goal attainment, while also noting possible publication bias and the need for more research.
Try This: Picture the desired result for one minute, name the most likely obstacle, then write: “If ___ happens, then I will ___.” For example, “If I feel anxious before checking my spending, then I will take three breaths and review only the last seven days.”
Step 4: Create a Short Daily Repetition Ritual
Repetition is what turns an occasional insight into a familiar response. Choose a short routine you can repeat at roughly the same time each day: after coffee, before work, after your evening shower, or when you sit down to review finances. Keep it simple enough that you can continue even on busy days.
A grounded five-minute ritual might include slow breathing, one believable abundance statement, a short visualization, one journal sentence, and one practical financial action. That action can be tiny: sending a follow-up email, checking a subscription, or setting tomorrow’s money priority.
The point is not to create a magical sequence. Repeated context-and-response pairings are relevant to habit formation, and habit research emphasizes the role of cues and repeated behavior in making responses more automatic.
Some readers prefer guided material rather than building a routine from scratch. The official sales page supplied for The Wealth Signal was not reliably accessible during verification, so specific claims about its current format, price, bonuses, or guarantee are intentionally omitted here.
If you want optional guided support for an abundance-oriented mindset routine, you can consider whether The Wealth Signal fits the way you prefer to practice and verify its current details on the official sales page before deciding.
Step 5: Pair Every Mindset Practice With One Real-World Money Action
This is the step that keeps abundance work grounded. If your practice changes how you feel but never changes what you do, it may remain comforting without improving the areas of life you actually care about. Choose one action that connects directly to your financial goal.
If you want more income, your action might be applying for a role, pitching a client, improving a portfolio, or reviewing your pricing. If you want more stability, it may be tracking spending, building an emergency fund, or setting a recurring savings transfer. If you run a business, it could be following up with leads or reviewing numbers you normally avoid.
A useful rule is one mindset practice, one measurable action. Meditate on abundance and still send the invoice. Visualize opportunity and still improve your résumé. Journal about receiving more and still study where your money goes.
Step 6: Work With Resistance Instead of Treating It as Failure
Old patterns usually do not disappear because you wrote a new affirmation once. You may still feel fear around debt, guilt when spending, or discomfort asking for more money. That does not mean the practice failed; it shows where the old pattern is strongest.
When resistance appears, use it as information. Ask, “What am I afraid would happen if I acted differently?” Then separate the emotional prediction from the practical reality. You might discover that you are not actually afraid of earning more; you are afraid of rejection when asking, uncertainty when trying something new, or responsibility if success increases.
Decision Check: Does your new belief help you take a healthier action while acknowledging reality? If yes, keep working with it. If it requires you to deny obvious facts or blame yourself for every setback, rewrite it.
Step 7: Review Evidence of Change Every Week
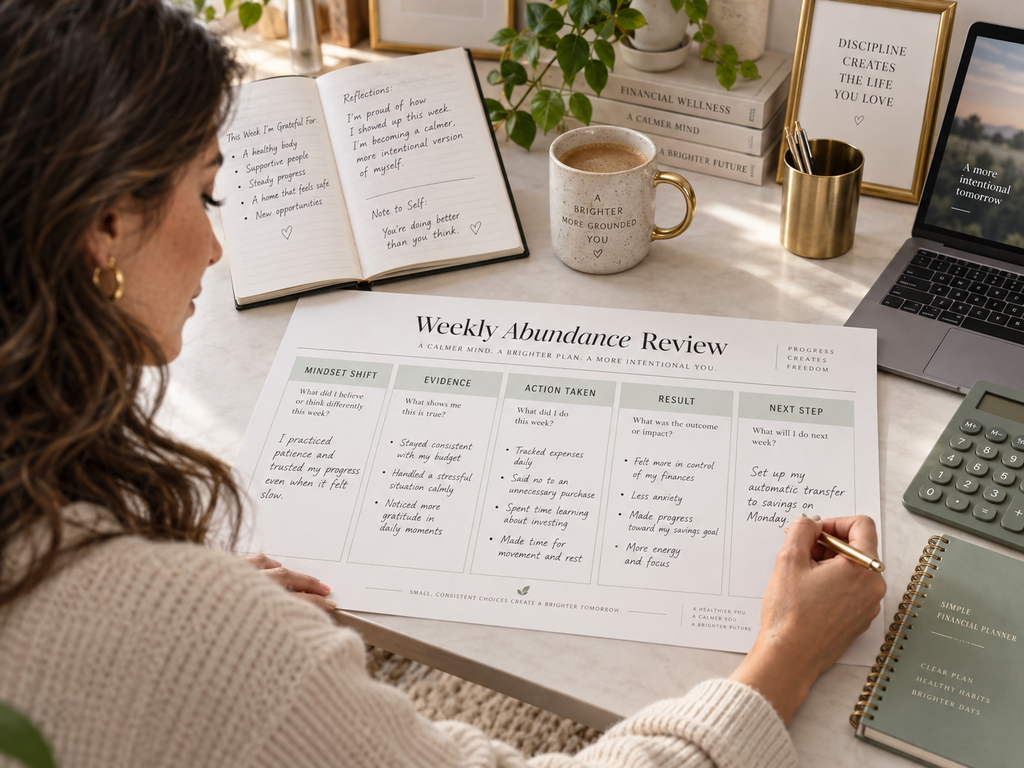
Abundance work can become vague when progress is measured only by mood or “signs from the universe.” Create a weekly review that includes both internal and external evidence. Internal evidence might include noticing a limiting belief faster, feeling calmer during money conversations, or recovering more quickly after a setback. External evidence should include actual behavior.
Track simple items such as applications sent, invoices followed up on, money saved, expenses reviewed, or hours spent building a useful skill. The purpose is not to turn spirituality into a spreadsheet; it is to give your mindset practice somewhere concrete to land.
This weekly review prevents the practice from becoming endless repetition without feedback. If the routine is helping you act more intentionally, keep it. If nothing changes except the wording in your journal, adjust the behavior component.
A Simple 10-Minute Subconscious Reprogramming for Abundance Routine
You do not need an elaborate ritual. A short routine that combines reflection and action is easier to sustain than a complicated practice that depends on perfect motivation.
- Minute 1–2: Settle. Breathe slowly and notice what money-related emotion is present.
- Minute 3: Name the old belief. Write the automatic thought without judging it.
- Minute 4: Reframe it. Choose a believable statement that creates room for action.
- Minute 5–6: Visualize behavior. Imagine yourself handling one specific financial situation well.
- Minute 7: Identify the obstacle. Name what could stop you today.
- Minute 8: Make an if-then plan. “If the obstacle appears, then I will take this response.”
- Minute 9–10: Act. Complete one small money-related task immediately.
This structure keeps the spiritual or reflective part connected to something observable. If you enjoy affirmations, meditation, audio, prayer, or visualization, you can place those practices inside the routine without expecting them to replace financial planning, skill development, work, or professional advice.
How Affirmations Fit Without Becoming Fake Positivity
Affirmations work best in this context when they support a more useful identity or action rather than make an unverifiable promise. “I am becoming someone who looks at my finances calmly” is more actionable than “money comes to me instantly.” “I can learn to ask for fair compensation” is more grounded than “wealth is guaranteed to find me.”
It is also worth distinguishing popular positive affirmations from psychological self-affirmation research. In psychology, self-affirmation often means reflecting on personally important values rather than repeating wealth statements. A meta-analysis found small positive effects of self-affirmation interventions on health-message acceptance, intentions, and behavior, but that research should not be stretched into evidence that abundance phrases directly produce financial outcomes.
Common Mistakes That Make Abundance Work Less Useful
The first mistake is trying to erase every “negative” thought. Useful mindset work does not require constant positivity; it requires enough awareness to choose your response. The second mistake is making the new belief so extreme that you do not believe a word of it.
The third mistake is using visualization instead of action. The fourth is measuring progress only through coincidences, synchronicities, or emotional highs. The fifth is blaming yourself when financial circumstances are difficult. Mindset can influence behavior, but income, debt, labor markets, family responsibilities, health, and access to opportunity are real external factors too.
Before You Do This: If a practice makes you feel responsible for every financial setback because you “thought wrong,” step away from that framing. A useful abundance practice should increase agency without turning hardship into self-blame.
Where The Wealth Signal May Fit Into the Routine
A product like The Wealth Signal may be relevant for readers who prefer guided structure instead of creating every reflection or listening practice themselves. Because the supplied official page could not be reliably accessed during verification, this article does not make claims about its current audio content, creator, modules, bonuses, price, guarantee, or delivery format.
That limitation does not prevent you from evaluating fit. Ask whether the product’s current official description supports the kind of practice you actually want: a consistent mindset routine, guided reflection, or another structured format. Then compare that with what you already have and whether you are likely to use it regularly.
If a guided abundance routine would help you stay more consistent than self-directed journaling alone, you can review The Wealth Signal’s current official description and decide whether its verified format matches that need.
The product should remain optional and should not replace budgeting, financial education, career action, business planning, or qualified financial advice.
How to Know Whether Your Practice Is Working
Do not ask only, “Do I feel more abundant?” Ask whether your relationship with money is becoming more functional. Are you avoiding fewer tasks? Are you making decisions with less panic? Are you following through on actions you previously postponed? Are you noticing opportunities because you are more engaged with your goals?
You might check your accounts without spiraling, negotiate instead of immediately accepting, or save consistently. Those changes are less dramatic than miracle stories, but they are easier to observe and build on.
For subconscious reprogramming for abundance, the best outcome is a loop: notice the old pattern, choose a better response, act, review what happened, and repeat. Over time, the healthier response can become more familiar.
Who May Benefit From a Structured Abundance Practice—and Who May Not
A structured routine may be useful if you like journaling, meditation, visualization, affirmations, or guided personal-development practices and want a consistent way to connect them with real-world action. It may also help if you understand your goals intellectually but repeatedly fall into the same avoidance patterns.
It may be less useful if you are looking for a guaranteed way to generate money without changing behavior, or if spiritual claims make you uncomfortable. In that case, you may get more value from straightforward goal-setting, budgeting, career development, business education, or professional financial guidance.
If The Wealth Signal’s current official materials match your preferred style of guided mindset practice, you can consider it as an optional layer of structure while keeping practical financial action at the center of your plan.
Subconscious Reprogramming for Abundance: The Bottom Line
Subconscious reprogramming for abundance is most useful when you treat it as a disciplined process of changing recurring beliefs, attention, habits, and behavior—not as a promise that thought alone will create wealth. Identify the automatic money story, build a believable reframe, visualize useful behavior, repeat the practice consistently, pair it with real action, work with resistance, and review evidence each week.
Spirituality can give the process meaning, hope, and intention. Psychology can offer useful ideas about habits, self-regulation, and goal pursuit. Practical financial behavior is what connects both to everyday life.
You do not need to choose between mindset and action. A grounded abundance practice uses mindset to support action, then uses action to give the new mindset evidence.
Can you really reprogram your subconscious for abundance?
“Subconscious reprogramming” is not one standardized scientific procedure. A grounded approach is to use repetition, reflection, habit change, and practical action to reshape recurring money beliefs and responses over time.
How long does subconscious reprogramming take?
There is no universal timeline. Different beliefs and habits change at different rates, so focus on consistent practice and observable behavioral progress rather than expecting a fixed number of days.
What is a good abundance affirmation?
Choose one that feels constructive and believable, such as “I can improve my financial habits one decision at a time” or “I am learning to respond to money with more clarity and confidence.”
Is visualization enough to create abundance?
Visualization can support reflection and goal focus, but it should not replace real-world action. Pair visualization with specific steps such as budgeting, skill building, applications, saving, or business activity.
Can I combine abundance practices with financial planning?
Yes. In fact, pairing mindset practices with concrete financial behavior keeps the routine more grounded and gives you clearer evidence of whether it is helping.
Where might The Wealth Signal fit?
It may be worth considering if its current official materials describe a guided structure that fits your preferred abundance practice. Verify the current product details directly before deciding, since they could not be reliably confirmed here.